Live homebuyer training — [WEBINAR DATE — NEEDS CONFIRMATION] · [WEBINAR TIME — ET]
You've built a real business.
Let me show you how business owners can explore financing for a home or rental property using income documentation suited to their situation.
A live training for self-employed and 1099 earners on how alternative-documentation home loans may let you qualify using business bank statements or other documents instead of tax returns, what cash you'd need to bring, and how to know your path before you shop.
“I'm self-employed too — on paper last year, my business looked like it lost money. I know how confusing that can feel when you're ready to buy a home. This training walks through the other options.”
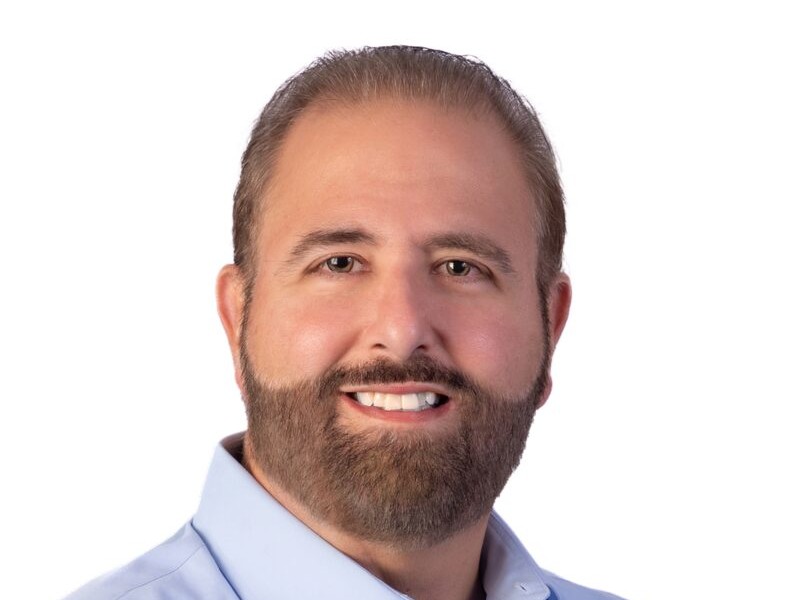
Joe Spellman
Branch Manager & Mortgage Loan Originator
Family First Mortgage USA, empowered by NEXA Lending
NMLS# 2142845 · Branch NMLS# 2729829
Don't miss out
When You Register, You'll Receive:
Hosted by Joe Spellman, Branch Manager & Mortgage Loan Originator · NMLS #2142845
- Live Training Access
- The Real-Income Review — a sample self-employed scenario walked through live (not a download)
- “Which Path Fits You” — bank-statement vs 1099 vs P&L vs asset-based vs conventional/FHA, live (not a download)
- Live Q&A With Joe
- Optional 1-on-1 Real Estate Strategy Call + written next-step plan
[CONSUMER CHARGE WORDING — NEEDS CONFIRMATION]
[001] — The problem
BUYINGAHOMEWHENYOUWORKFORYOURSELFSHOULDNOTFEELLIKEDECODINGFINEPRINT.
When you run your own business, the same write-offs that keep your books healthy can make income look smaller on paper. The good news: there may be other ways a lender can look at what a business earns. This training lays out, in plain English, how alternative-documentation loans work, what they ask of you, and how to figure out which path to explore first.
[002] — A note from Joe
To every business owner who's ever wondered how lenders look at their income,
“If my tax return shows low income, I can't buy a home.”
“Every lender looks at a business owner's income the same way.”
“I have to wait two years and pay more tax before I can qualify.”
A tax return is one way to show income — not the only one. Some loan programs may look at business bank statements, 1099s, a CPA-prepared P&L, or assets instead, subject to lender requirements.
Lenders don't all read a business owner's file the same way, either. Conventional and FHA guidelines lean on what's left after write-offs; alternative-documentation (non-QM) programs are built around other documents. The program you start with can change the picture.
Waiting two years and changing how you file is one option — for some people it's the right one. But it isn't the only one worth understanding. These loans come with honest trade-offs: they generally need more cash up front and may cost more than FHA or first-time-buyer programs, and you deserve to see that clearly before you decide anything.
That's what this training is for: education first, so you can make a calm, informed decision alongside your own CPA and advisors.
— Joe Spellman, Family First Mortgage USA, empowered by NEXA Lending
[003] — Who it's for
This training is
designed for:
Business Owners Exploring Options Beyond Tax Returns
1099 Earners Who Want A Clearer Process
Ready To Stop Renting And Buy Your Family's Home
Owners Who'd Like A Second Look At Their Options
Homeowners Who Want To Review Refinance Or Consolidation Options
STEP 01
Reserve
Save your seat in under a minute — name, email, mobile and state.
STEP 02
Watch
Join Joe live on Zoom for the training and live Q&A.
STEP 03
Prepare
Know the documents and cash picture we walk through live.
STEP 04
Decide
Pick a path to explore first — or book an optional strategy call.
[004] — Curriculum
Get a sneak peek
into the webinar
5 MODULES · 60 MIN (≈40-MIN TRAINING + LIVE Q&A) TOTAL
[005] — Your host
Joe SpellmanBranch Manager & Mortgage Loan Originator
Joe Spellman · Branch Manager & Mortgage Loan Originator
Guidance from someone who works inside the process.
I've spent [YEARS IN LENDING — NEEDS CONFIRMATION] on the lending side of the table, and today I'm a branch manager with Family First Mortgage USA. A lot of the people I talk to look a lot like me: they run real businesses, they pay their bills, and their tax returns don't always tell the whole story of what their business earns.
I'm self-employed too, so I know how write-offs that make sense for a business can make income look smaller on paper. What helps most is understanding that there may be more than one way to document income — and what each path really asks of you.
This training is the conversation I wish every business owner got before they started shopping: how alternative-documentation and DSCR loans work, the cash they generally require, the honest trade-offs, and how to figure out which path fits. Education first — the decisions stay yours.
COMPANY
Family First Mortgage USA, empowered by NEXA Lending
NMLS#
Personal NMLS #2142845
CO. NMLS#
Branch NMLS #2729829 · NEXA Lending LLC NMLS #1660690 · NMLS Consumer Access
LICENSED IN
[LICENSED STATES — NEEDS CONFIRMATION · Florida confirmed]
320+
Lenders shopped
9–16 day
Average close
5.0
Google rating (55+ reviews)
[006] — Sound familiar?
If you're like most self-employed owners I work with…
You've built something real. Clients pay you, payroll goes out, the business grows. When it's time to buy a home, it's natural to wonder how a lender will look at all of that — and which numbers actually count.
That's where clear answers help: why write-offs matter, which documents may be used, and whether there's more than one path to look at. You don't need to change how you run your business to understand your options.
HERE'S WHAT CHANGES AFTER THIS WEBINAR:
- You'll understand how lenders can look at a business owner's income beyond the tax return
- You'll know the cash and documents to have ready before you start house-hunting
- You'll leave knowing which loan path to explore first, and why
[007] — Takeaways
What you'll walk away with
Clearer View
How lenders may look at self-employed income beyond the tax return.
Your Document List
Walked through live — no download.
Questions to Ask
What to ask any lender before you apply anywhere.
Optional Next Step
Book a Real Estate Strategy Call if you'd like a written next-step plan.
[008] — FAQ
Common questions
[009] — Book a call
Your next move starts with a clearer map.
- Live training with Joe on Zoom
- Live Q&A included
- Educational event — not a loan application
- Optional 1-on-1 Real Estate Strategy Call afterward
Joe Spellman, Branch Manager & Mortgage Loan Originator · Family First Mortgage USA, empowered by NEXA Lending · NMLS #2142845
[CONSUMER CHARGE WORDING — NEEDS CONFIRMATION]